🔔 Why this matters now
Q: Why is multi-currency harder for EdTech than for other startups?
Because the money arrives in small amounts, from many countries, through payment platforms. A software company bills twenty enterprise clients. An EdTech platform might collect from thousands of parents, dozens of schools and a few government contracts. The money arrives in several currencies, days later, net of fees. Each flow has its own rate date and its own tax treatment.
Q: What changed for digital learning services?
The VAT rules tightened. An amendment to Article 31 of the VAT Executive Regulation took effect on 15 November 2024. It blocks zero-rating for electronic services used and enjoyed inside the UAE, even when the customer sits overseas. For a platform selling learning content, the learner’s location now matters more than the billing address.
| 📋 EdTech Currency Checklist | ||
|---|---|---|
| AREA | WHAT TO FIX | RULE |
| Conversion method | Pick one and document it | Central Bank rates, applied consistently |
| FX gains and losses | Decide realised or realisation basis | Both are in taxable income by default |
| VAT on digital services | Map users by location | Place of supply follows use and enjoyment |
| Foreign currency invoices | Show the AED amount and rate | Otherwise the customer loses input VAT |
| Deferred revenue | Split annual plans by month | Cash collected is not revenue earned |
| E-invoicing | Appoint a provider | Go-live from 1 January 2027 |
- Control 1
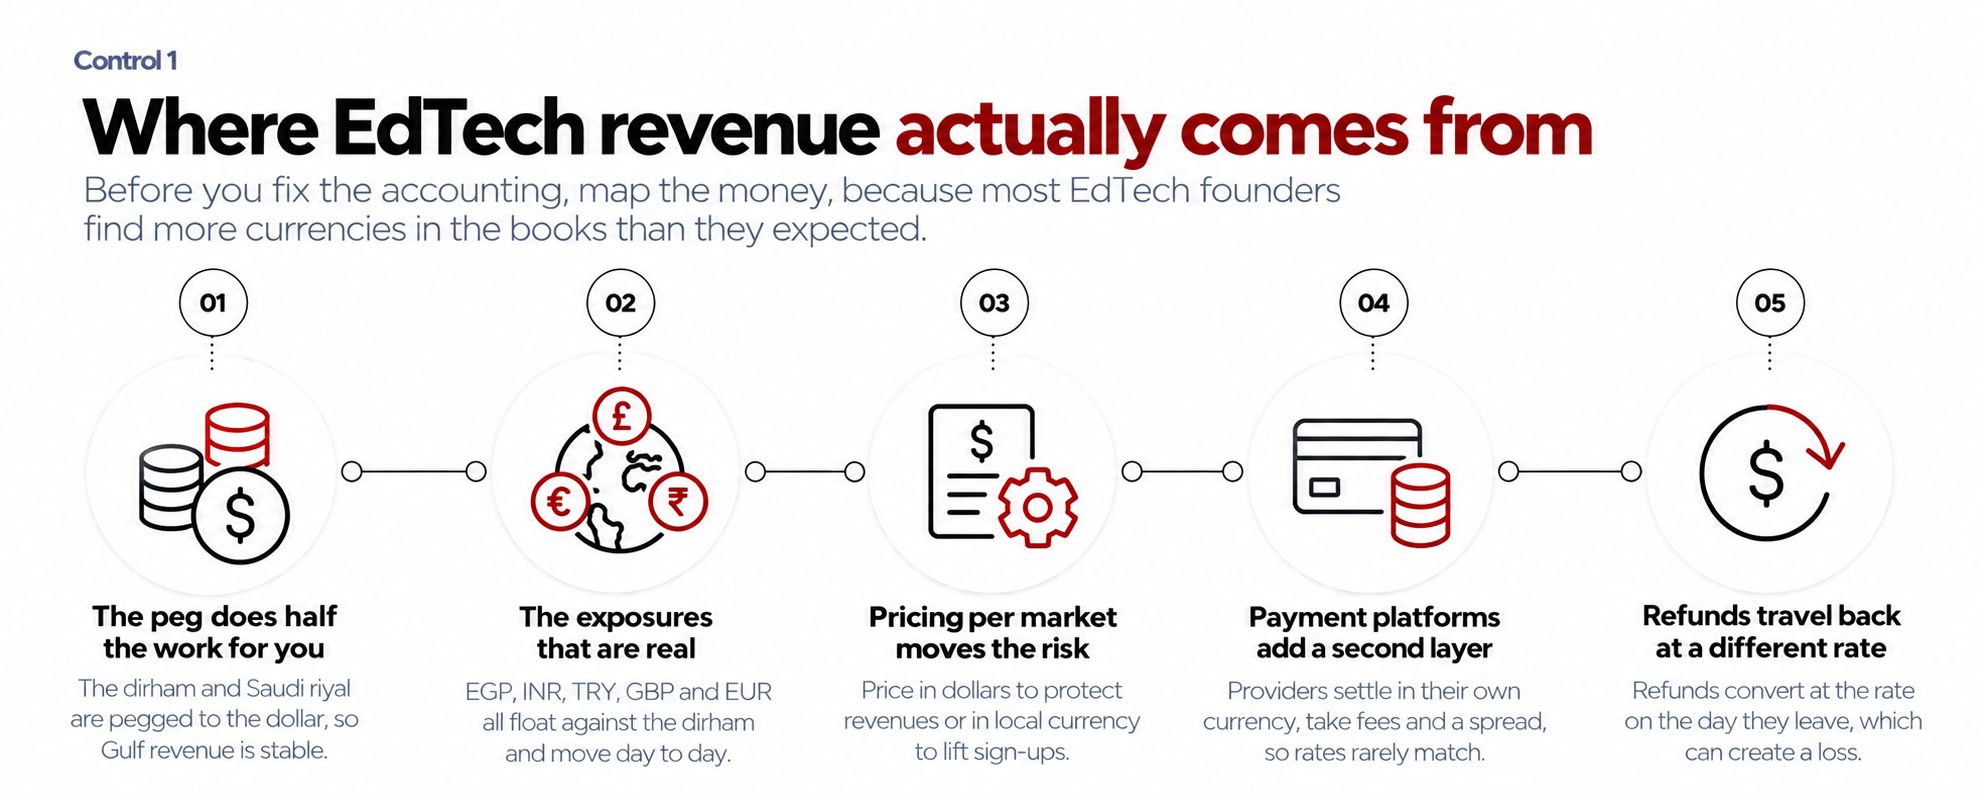
Where EdTech revenue actually comes from
Before you fix the accounting, map the money, because most EdTech founders find more currencies in the books than they expected.
The peg does half the work for you
The dirham has held a peg of 3.6725 to the US dollar since 1997, so revenue billed in dollars carries no real risk for a UAE firm. The Saudi riyal is also pegged to the dollar, so Gulf revenue is largely stable in dirham terms.
The exposures that are real
Everything else moves day to day, because Egyptian pounds, Indian rupees, Turkish lira, pounds sterling and euros all float against the dirham. A platform that prices an annual subscription in a floating currency carries that movement for twelve months. It often takes the cash upfront, long before it spends on delivery.
Pricing per market moves the risk
Many platforms price once in dollars and let local buyers absorb the swing. That protects the books and can cost you sign-ups at the checkout page. Pricing in local money lifts sign-ups and moves the risk onto your side. Both are valid choices. The costly pattern is drifting between them market by market with no written policy.
Payment platforms add a second layer
Card schemes and payment providers settle in their own money, on their own timetable, and they take fees and a spread on the way. The rate you booked at the sale and the rate you banked rarely match. That difference belongs in the model, not in a rounding line.
Refunds travel back at a different rate
EdTech refunds are common. Term cancellations, dropped cohorts and parent chargebacks all send money back out. The refund converts at the rate on the day it leaves, which is not the rate that applied when the sale landed. A platform with heavy term-time refunds can book a loss on money it never kept.
✅ Action to Take
Build a one-page map of revenue by currency, collection method and settlement lag before changing anything else. Companies that want that view maintained monthly keep it inside virtual CFO support alongside the management accounts.
- Control 2
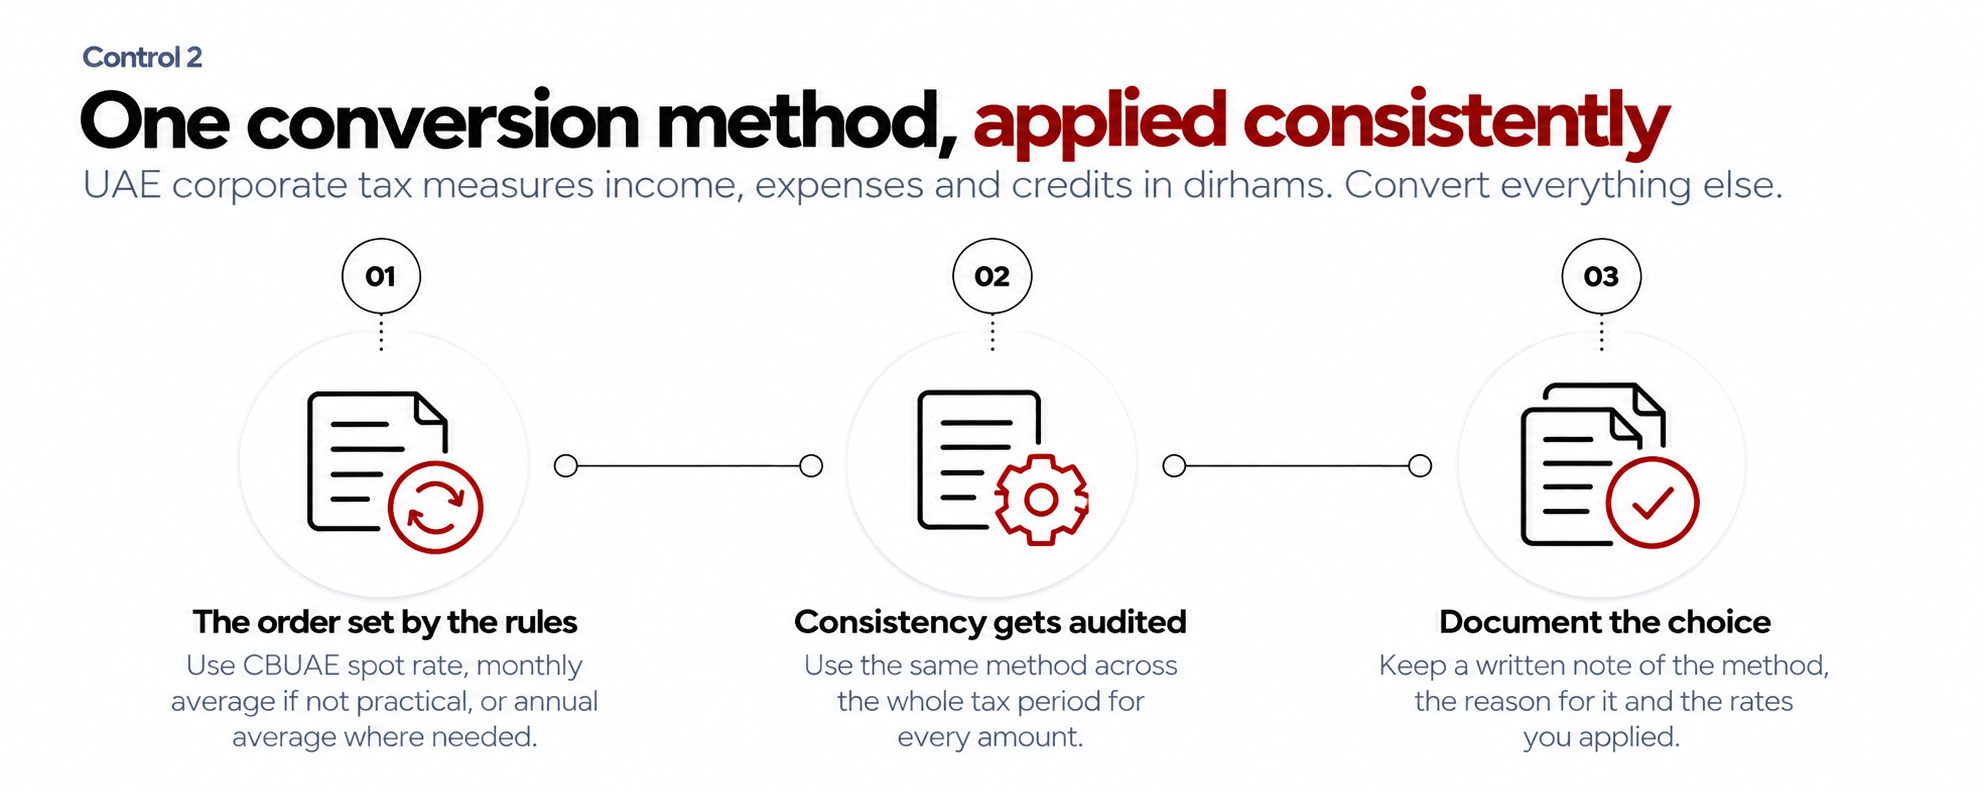
One conversion method, applied consistently
UAE corporate tax measures income, expenses and credits in dirhams. Convert everything else.
The order set by the rules
Use the exchange rates set by the Central Bank of the UAE. Guidance gives an order. Use the spot rate on the deal date where your system can do it, and where that is not practical, use the Central Bank monthly average. Where neither works, use the annual average.
Consistency is the part that gets audited
Apply the chosen method across the whole tax period, to every relevant amount. Switching between spot and average rates inside a year creates gaps nobody can explain later. Many platforms also keep a dollar view for investors next to the dirham books, which the peg makes simple.
Document the choice
Keep a written note of the method, the reason for it and the rates you applied. Keep corporate tax records for seven years after the end of the tax period, so the note has to outlive whoever wrote it.
✅ Action to Take
Write a one-page currency policy. Name the method, the rate source and the review date, then apply it from the next close. Tidy multi-currency books through structured accounting services keep the policy visible in the ledger.
- Control 3
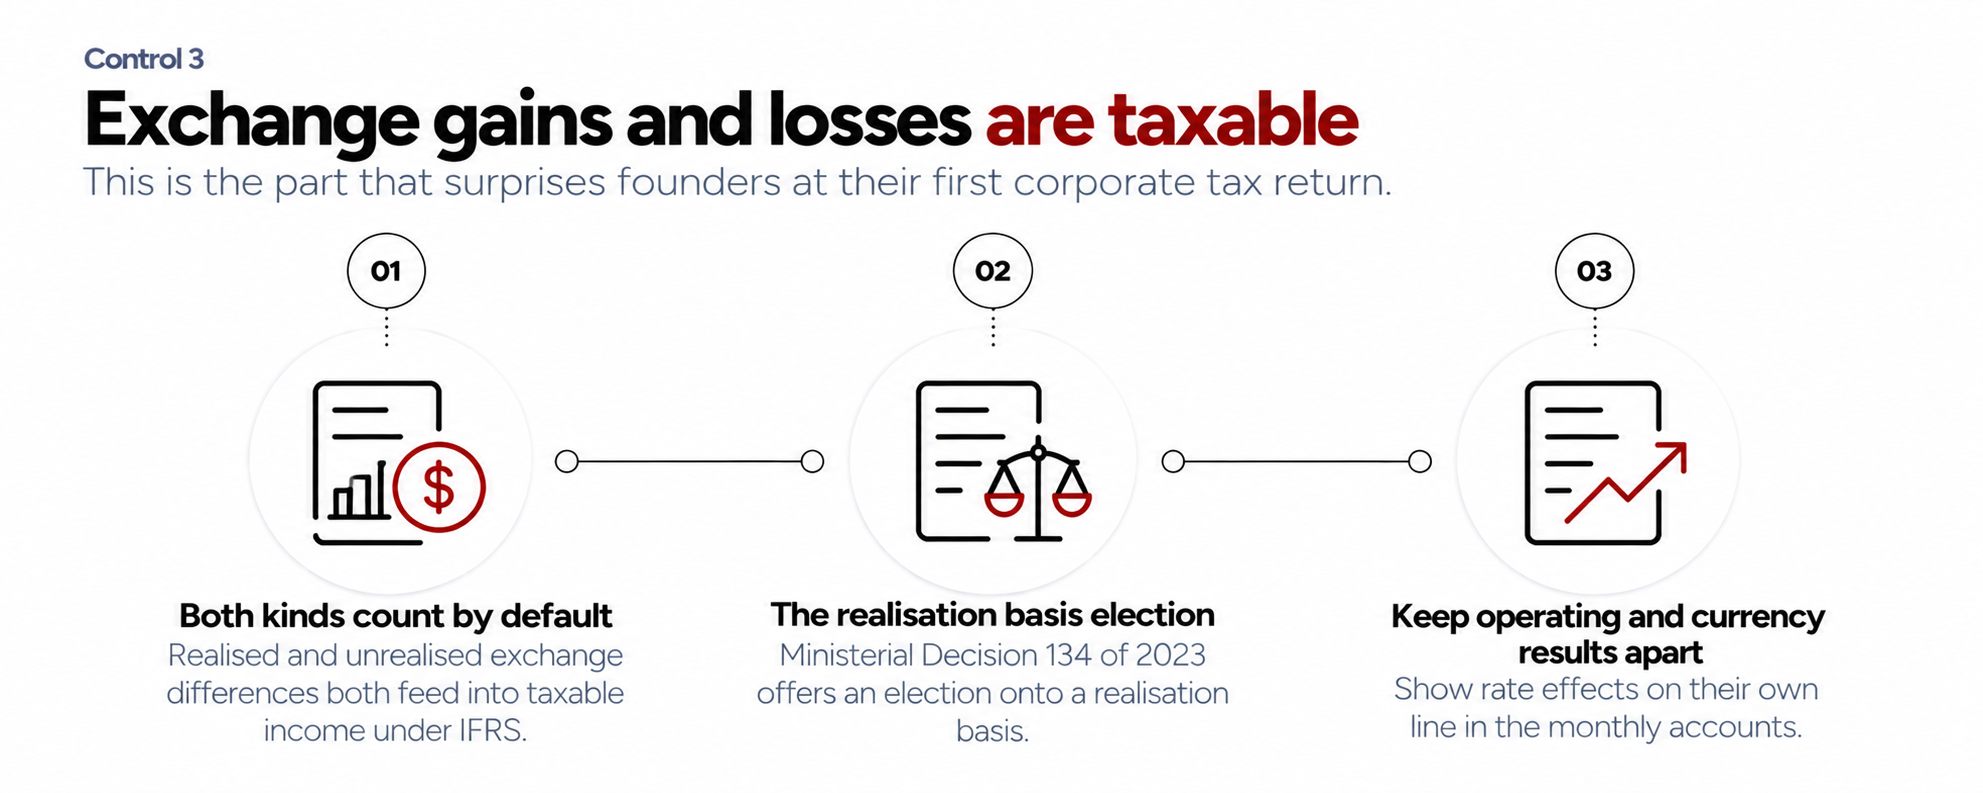
Exchange gains and losses are taxable
This is the part that surprises founders at their first corporate tax return.
Both kinds count by default
UAE corporate tax starts from accounting profit prepared under IFRS. Under the default position, realised and unrealised exchange differences both feed into taxable income. A dollar balance revalued at year end can create tax on a gain you have not banked.
The realisation basis election
Ministerial Decision 134 of 2023 offers an election onto a realisation basis. That election holds back unrealised gains and losses until they become real. The election reaches other unrealised items too, so weigh the whole position before making it.
Keep operating and currency results apart
An EdTech platform can post a strong month and a weak result because sterling moved. Show rate effects on their own line in the monthly accounts. Investors and boards read the trend faster when the noise sits somewhere visible.
✅ Action to Take
Separate exchange movement from operating performance in the monthly pack. Review the realisation election before you file the first return. Firms wanting senior judgement on that call bring in a fractional CFO before the filing window.
- Control 4
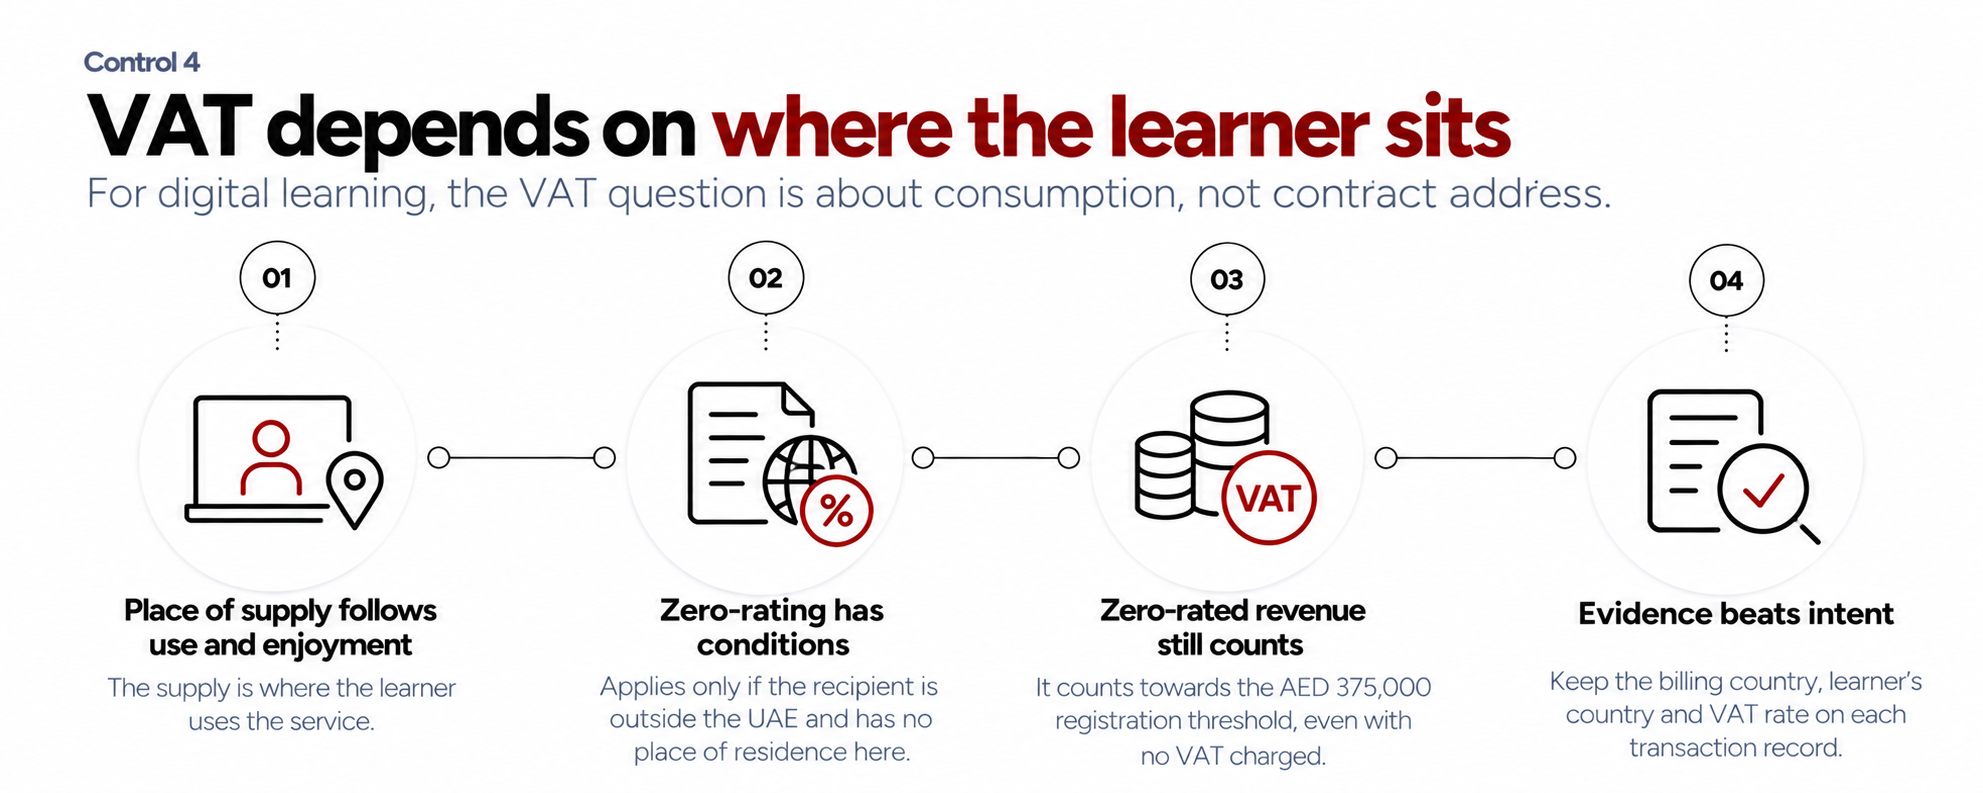
VAT depends on where the learner sits
For digital learning, the VAT question is about consumption, not contract address.
Place of supply follows use and enjoyment
For electronic services, the place of supply follows where the learner uses the service. A learner in Dubai takes the course, so the supply happens in the UAE, and who paid for it does not change that.
Zero-rating has conditions
Article 31 of the VAT Executive Regulation zero-rates exported services on two conditions. The recipient holds no place of residence in an implementing state. They also sit outside the UAE while the service runs. Since 15 November 2024, electronic services used and enjoyed inside the UAE fall outside that treatment. A single global price list with no location data behind it makes the call impossible to prove.
Zero-rated revenue still counts
Registration becomes mandatory once taxable supplies pass AED 375,000, and zero-rated supplies count towards that threshold. An EdTech selling only to schools abroad can still need to register while charging no VAT, and registration opens input VAT recovery on hosting, content and marketing.
Evidence beats intent
The treatment you pick has to be provable at the point of sale. Keep the billing country, the learner’s country and the VAT rate applied on each transaction record. A platform that can pull that report in one click answers an FTA query in a day. One that cannot spends a week rebuilding it from card data.
✅ Action to Take
Tag every sale with the learner’s location and the VAT treatment applied, from the first invoice of the period. Founders with cross-border revenue confirm the treatment with specialist corporate tax advice before the next return.
- Control 5
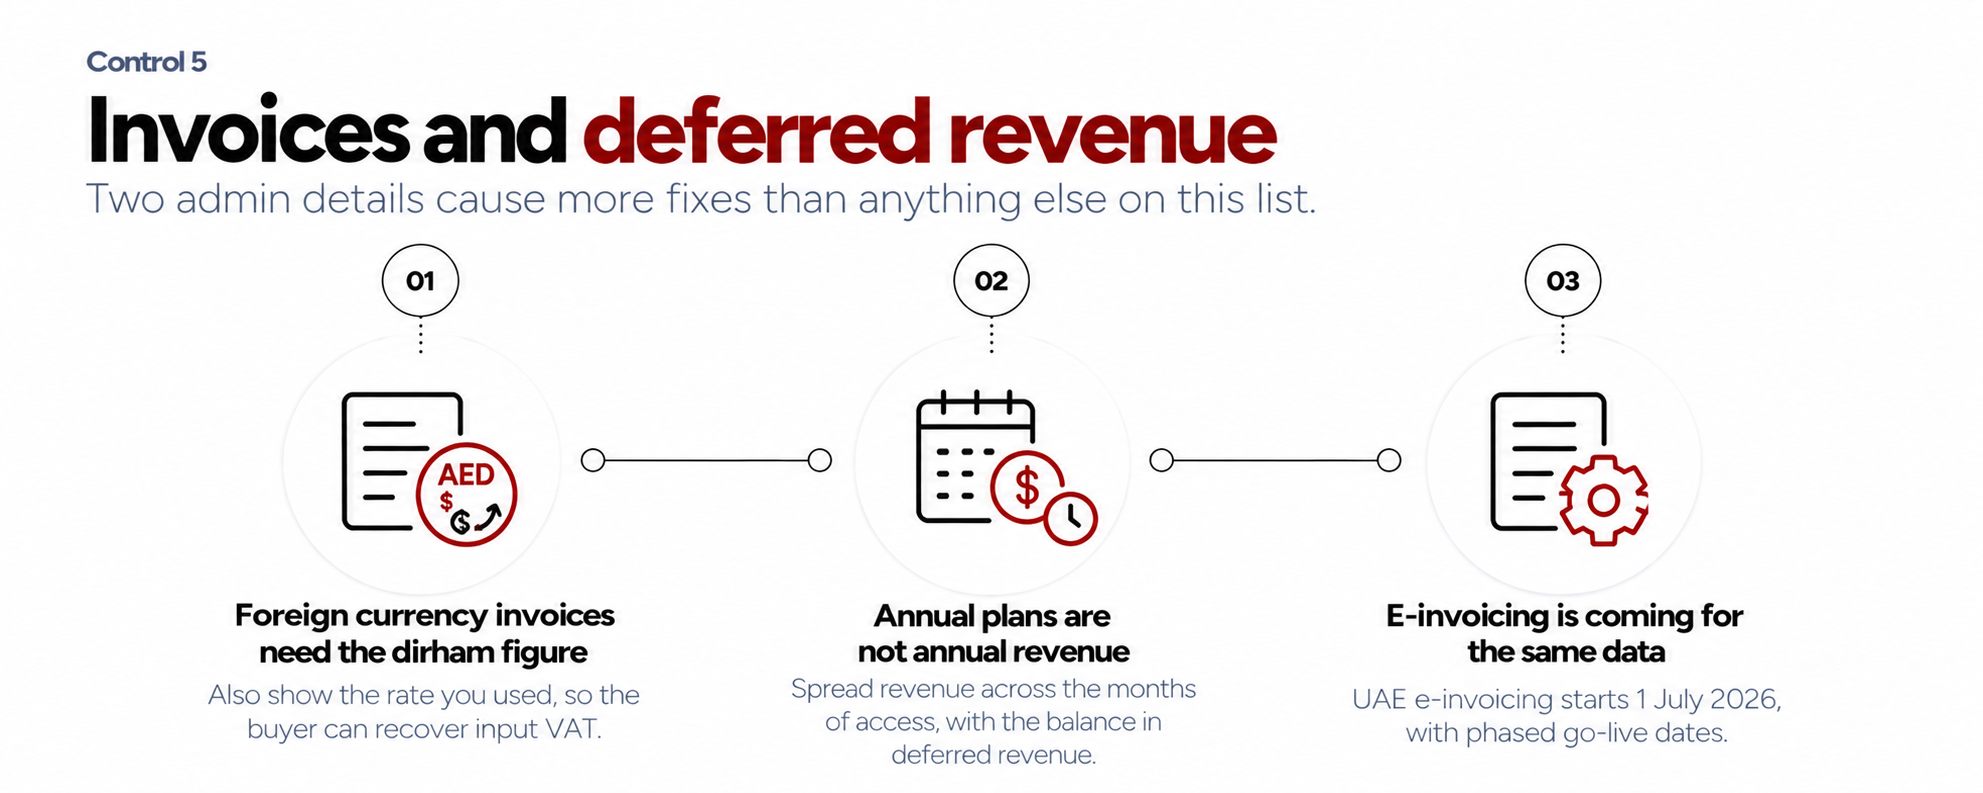
Invoices and deferred revenue
Two admin details cause more fixes than anything else on this list.
Foreign currency invoices need the dirham figure
You may issue a tax invoice in another currency, but it must also show the dirham amount and the rate you used. Without them the buyer cannot recover input VAT, and the query lands in your inbox weeks later. Set the billing system up once and the problem goes away.
Annual plans are not annual revenue
EdTech sells school years. Cash arrives in August for twelve months of access. Accrual accounting spreads that revenue across the months of access, and the balance sits as deferred revenue until you earn it. A platform that reads its bank balance as results will misread August and panic in February.
E-invoicing is coming for the same data
The UAE e-invoicing pilot began on 1 July 2026. Businesses with revenue of AED 50 million or more appoint an accredited service provider by 30 October 2026. Go-live is 1 January 2027. Everyone else appoints by 31 March 2027 and goes live on 1 July 2027. The Ministry of Finance portal carries current guidance. Clean rate and country data on invoices makes that switch far cheaper.
✅ Action to Take
Audit one month of issued invoices against the currency, dirham conversion and location fields before the next VAT return. Early firms that build this properly the first time use startup CFO support before a fix is needed.
Not sure which currencies are actually costing you money?
A short call on your revenue mix and settlement flows will show where the leakage sits.
- Control 6
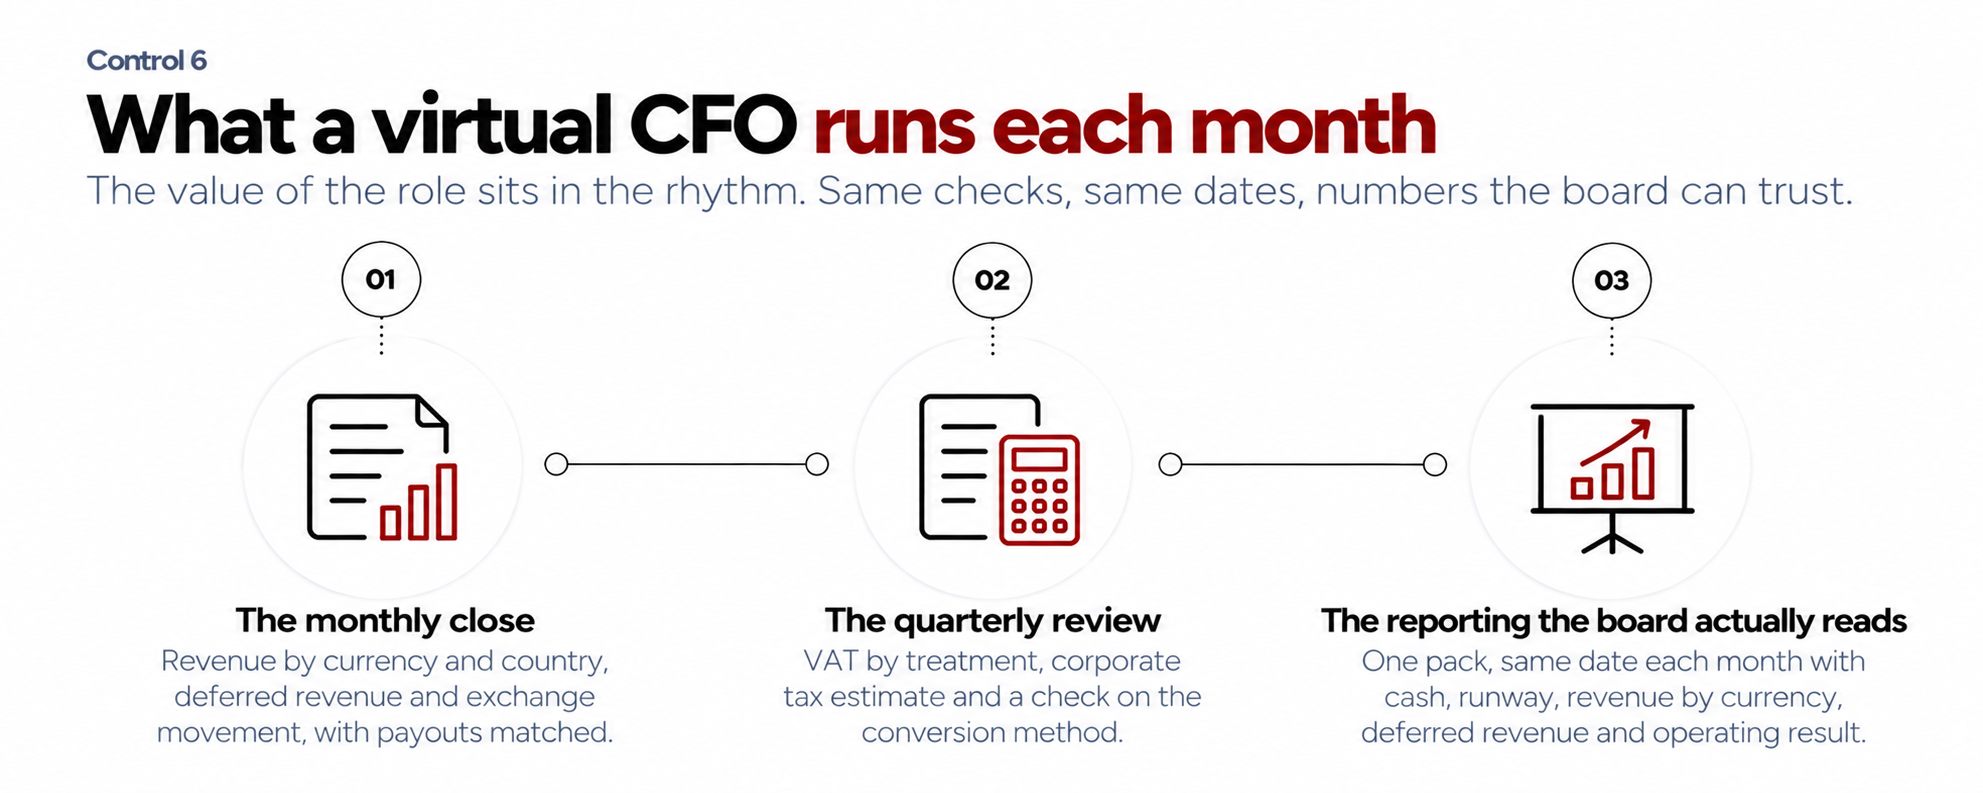
What a virtual CFO runs each month
The value of the role sits in the rhythm. Same checks, same dates, numbers the board can trust.
The monthly close
Revenue split by currency and by country. Deferred revenue schedule updated. Exchange movement on its own line. Match payment payouts to gross billings, so fees and spreads show up.
The quarterly review
VAT picture by treatment. Corporate tax estimate for the year. A check that the ledger still follows the written conversion method. Any change in where learners sit gets picked up here, before it becomes a filing question.
The reporting the board actually reads
One pack, one format, sent on the same date each month. Cash, runway, revenue by currency, deferred revenue and the operating result with the rate noise stripped out. For a company raising, this pack is the data room in progress.
✅ Action to Take
Fix the close calendar and the pack format now, then keep both unchanged for four quarters so trends become readable. Firms needing this rhythm without a full-time hire use scheduled part-time CFO time to run it.
Common Questions
Short answers to what UAE EdTech founders ask about multi-currency revenue.
Dirhams for corporate tax, because the law measures income, expenses and credits in AED. Many platforms also track a dollar view for investors, which the peg makes easy.
Rates set by the Central Bank of the UAE. Use the spot rate on the transaction date where your system supports it, then the monthly average, then the annual average.
No. The chosen method applies across the whole tax period. Changing it mid-year creates gaps that are hard to explain and harder to defend.
By default, yes, because they sit in accounting profit. Ministerial Decision 134 of 2023 allows an election onto a realisation basis, which defers them until they crystallise.
It depends on where the learner uses the course, and a learner inside the UAE makes it a UAE supply whatever the invoice address says.
Possibly. Zero-rated supplies count towards the AED 375,000 registration threshold, so an exporter can cross it while charging no VAT.
Yes. The tax invoice must also show the dirham amount and the exchange rate used, otherwise the customer cannot claim input VAT.
Across the period of access, not on collection. The unearned portion sits as deferred revenue, which also keeps monthly performance readable.
Rarely worth it at early stage for pegged currencies. For floating currency revenue, a shorter cash cycle and regular price reviews usually do more than a hedging product.
Treat the term calendar as a cash calendar. Institutional buyers often pay against their own budget cycle, so a summer invoice may settle in October. Build that lag into the forecast before it shows up as a cash surprise.
Once revenue arrives in more than one currency, or once a raise or audit is in view. Both create reporting demands that monthly book-keeping alone cannot answer.
It follows scope more than title. Our guide to fractional CFO cost in the UAE sets out how to compare quotes on like-for-like terms.
Multi-currency revenue is a data problem before it is an accounting problem. Location on the invoice, currency on the transaction, rate on the conversion, and a schedule behind every annual plan. Get those four fields right at the point of sale. The VAT position, the tax return and the investor pack then follow from one source. Most of that work happens once, inside the billing system. Get them wrong and every quarter starts with a clean-up nobody budgeted for.
JaZaa CFO Advisory Team
The JaZaa CFO Advisory Team works with startups and SMEs across the UAE on multi-currency reporting, tax compliance and management accounts. Members hold US CMA, MBA and capital market qualifications, with backgrounds in financial modelling and capital structuring.
Legal disclaimer
This article provides general information about multi-currency reporting, VAT and corporate tax for EdTech startups and SMEs in the UAE. It does not constitute professional financial, tax, or accounting advice specific to your business. JaZaa provides professional business services including accounting, bookkeeping support, and management consulting. We are not a registered audit firm, tax agent, CPA, or Chartered Accounting firm. VAT treatment of digital services depends on user location and contract terms. Confirm the position for your situation. Reading this article does not create an advisor-client relationship with JaZaa. For advice specific to your situation, arrange a consultation.